In today's update, HMRC has issued critical guidance for sole traders and landlords transitioning to Making Tax Digital, warning of split payment records. The tax authority has also highlighted a widespread failure among company directors to file Corporation Tax returns on time. Additionally, we cover new online exception forms for employers and upcoming Capital Gains Tax reliefs.
HMRC warns MTD taxpayers of split online payment accounts
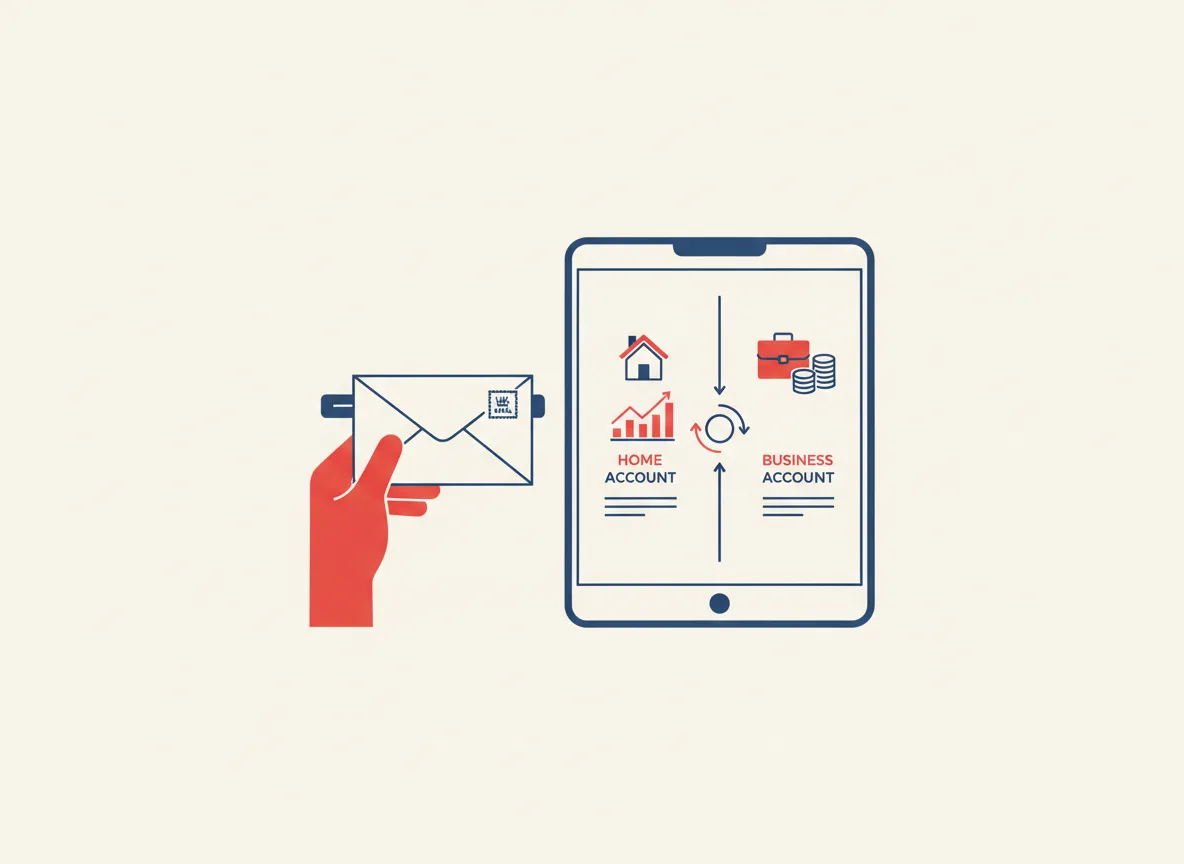
HMRC has begun sending letters to sole traders and landlords with incomes over #50,000 who are transitioning to Making Tax Digital (MTD) for Income Tax from 6 April 2026 [0, 1]. The letters warn that their Self Assessment payment information may be split across two separate online systems: their existing Self Assessment account and the new MTD service [0, 1].
If a payment is marked as 'transferred to digital' in the traditional Self Assessment account, it has been moved to the MTD service and will typically appear under the 'what you owe' section [0, 1]. HMRC has clarified that transitioning to MTD does not alter the total amount of tax owed, the payment methods, or the 31 January 2027 deadline for balancing payments [1].
Why it matters: If you are a sole trader or landlord transitioning to MTD, you must check both online accounts to ensure your payments are correctly recorded and avoid missing outstanding balances.
Sources: rossmartin.co.uk · litrg.org.uk
Over 100,000 companies miss Corporation Tax filing deadlines annually
HMRC has revealed that more than 100,000 companies fail to file their Company Tax return within 12 months of their statutory filing date each year [2, 3]. As of May 2026, over 20,000 companies had returns that were outstanding by more than a year [3].
Directors are reminded that they are legally required to submit a Company Tax return even if their business has no Corporation Tax to pay [3]. Failure to do so results in late filing penalties and the risk of HMRC issuing estimated tax determinations [3].
Why it matters: If you run a limited company, you must file your Corporation Tax return on time even for a dormant or loss-making business to avoid automatic penalties and estimated bills.
Sources: www.gov.uk · www.gov.uk
New online form launched for globally mobile employee benefits exception
HMRC has launched a new online exception cases service to help employers manage benefits in kind for globally mobile staff [2, 3]. The service, which went live on 5 November 2026, allows employers to exclude eligible globally mobile employees from mandatory payrolling of benefits [3].
To apply the exclusion, employers must complete the new online form to notify HMRC [3]. For any excluded employees, businesses must continue to report benefits using the traditional year-end P11D and P11D(b) forms [3].
Why it matters: If you employ globally mobile staff and want to exclude them from mandatory benefit payrolling, you need to submit the new online form and maintain traditional P11D reporting.
Sources: www.gov.uk · www.gov.uk
HMRC outlines new Capital Gains Tax Founder's Relief for April 2027
Following the Autumn Budget 2026, HMRC has outlined a new Capital Gains Tax (CGT) relief targeted at business founders and early-stage investors [2, 3]. The relief will apply to qualifying disposals of shares or securities in high-growth, innovative companies starting from 6 April 2027 [3].
This measure is designed to stimulate investment in high-growth enterprises [3]. HMRC has indicated that further details regarding specific eligibility criteria will be published in future updates [3].
Why it matters: If you are a founder or early investor in an innovative company, you should monitor the upcoming eligibility rules to see if your future share disposals qualify for this relief.
Sources: www.gov.uk · www.gov.uk
This digest was compiled automatically with AI from public sources on 2026-11-20. It is general information, not tax or legal advice — check the linked sources (and your accountant) before acting.